Do you remember Dunzo? There was a time when you could get absolutely anything delivered to your house in twenty minutes, medicines, phone chargers, a single onion at 2 am from this app. Then delivery slowed, salaries got delayed and the app quietly stopped working for most individuals. Dunzo was one of those names that people bring up when the issue of “startups that flopped” comes up.
Here’s the part nobody talks about though. In August 2025, Dunzo Digital Private Limited was legally admitted into insolvency proceedings by the NCLT.1 So, even though the majority of us had deleted the app from our phones a year or two ago, the real corporation was still around, caught in the middle of legal battles, months after everyone thought it has vanished.
Which raises a really puzzling question. If the app is gone, the office is empty and nobody’s getting deliveries anymore, is the company dead? Not really. And the ‘why’ is a fairly interesting rabbit hole to explore.
A company can go quiet long before it’s actually dead
Take Hike. Its messaging app was shut down in January 2021, and that was the end of it for the majority of us.2 Hike was done. Except the company behind the app didn’t disappear the second the app stopped working.
That’s because a company is an individual legal entity, separate from its product, its founders and its social media pages. It can have zero users and no buzz yet nevertheless exist on paper, filing its returns year after year as if nothing occurred.
So the actual hierarchy goes something like this: the product usually dies first, then maybe the business dies, and only seldom does the company itself truly perish. None of the steps are mandatory. You can lose a product, not lose the business, and lose the business, not lose the company.
Here’s a quick gut check that most people get wrong:
| What actually happened | Is the company legally dead? |
| The app was shut down | No |
| The business stopped operating | Not necessarily |
| The company went inactive | No |
| The company was struck off | Yes |
| The company was dissolved after liquidation | Yes |
So how does a company actually die, legally?
There is no one universal off switch. Depending on why a company is closing and who is making the decision, it can end in one of four very different ways.
Route one: strike-off, the simplest exit – This is effectively the corporation saying, “We are done; please remove our name from the list.” Under Section 248 of the Companies Act, 2013, a company that has truly ceased doing business and meets certain conditions may apply to have its name removed from the Register of Companies.3 The government sped up the process by launching C-PACE in May 2023, and by mid-2025, most applications were allegedly being cleared in less than two months.4 That being said, this isn’t an easy way to ghost your responsibilities. You still need to pay your dues, file declarations, and tie up loose ends before the Registrar releases you.
Route two is voluntary liquidation, which allows you to close on your own terms. This is more serious than strike-off. Section 59 of the Insolvency and Bankruptcy Code, 2016 (“IBC”) allows a corporation to wind up its own affairs rather than waiting for someone to compel its hand.5 A liquidator takes over, sorts through the company’s assets and liabilities, settles claims, and dissolves the entity. This happens more frequently than people think. Every month, many small and medium-sized businesses go through this discreetly and without making any headlines.6 It serves as a good reminder that not every company that dies was pushed. Some of them simply decide it is time to depart.
Route three: NCLT winding up, where the law forces you. Section 271 of the Companies Act, 2013 allows the NCLT to order the winding up of a business based on particular statutory grounds such as incapacity to pay debts, fraud, or the company acting against the public interest.7 The difference here is in tone. The tribunal, not the company, has made the decision to shut its operations. Once that order is issued, a liquidator takes over, reviews the firm’s affairs, sells what can be sold, settles with liabilities, and eventually dissolves the company.
Route four: insolvency occurs when debts accumulate. This is where we can take the examples of BluSmart and Byju’s, although for very different reasons. BluSmart Mobility Tech was placed into Corporate Insolvency Resolution Process (“CIRP”) before the NCLT’s Ahmedabad bench in October 2025 after a creditor filed a claim under Section 9 of the IBC.8 When CIRP steps in, the company’s board of directors loses control and a resolution expert takes over. Byju’s is a more dramatic expression of the same concept. Its parent company, Think and Learn, was referred to CIRP in July 2024 due to an unpaid sponsorship issue, and more than two years later, the case is still pending appeals, committee disagreements, and suspended bidding processes.9
The most common myth concerning insolvency is that entering CIRP means a company is done for. The goal of the process instead is to first determine whether the company can be rescued. If a resolution plan is successful, the company survives, possibly with new ownership. Only when all else fails does liquidation become an option.
What actually happens once liquidation kicks in
Picture a company shutting down. It has cash in the bank, unpaid invoices, a few laptops and furniture, maybe a trademark or two, employees who are owed pay cheques, a bank that loaned it money, vendors who are still waiting to be paid, and a tax department that always pops up somewhere on the list.
The liquidator’s role is to answer a few rather unglamorous questions. What does the company really own? What is its debt? To whom? What can be sold and for what price? And most crucially, who gets paid first?
That last question is not a matter of luck. Section 53 of the IBC provides a predetermined order of precedence, frequently referred to as the waterfall mechanism, with some dues, such as costs of insolvency and wages of workmen, ranking higher than others, such as unsecured creditors or shareholders.10 The money is divided in that order. The affairs of the company are wound up and it is formally dissolved. That’s the real finish line.
So when is a company REALLY dead?
Put all these stories side by side and the picture becomes apparent. Hike’s product disappeared, but that didn’t kill the company on its own. The familiar Dunzo app vanished long before the legal company went through a formal process. BluSmart stopped running taxis the moment CIRP began, but this is a rescue operation, not a funeral. Byju’s insolvency process has been ongoing for more than two years, indicating that CIRP is frequently the start of a very long battle, not the end of one. And somewhere in the background, thousands of ordinary companies go through strike-off or voluntary liquidation every year without anyone noticing, because that’s what a clean exit should look like.
One thing to remember from all of this is that CIRP and liquidation are not interchangeable terms. The rescue effort is CIRP. If that rescue doesn’t work out, it’s liquidation. Get that one difference down, and honestly, you know more about corporate death than most people ever bother to.
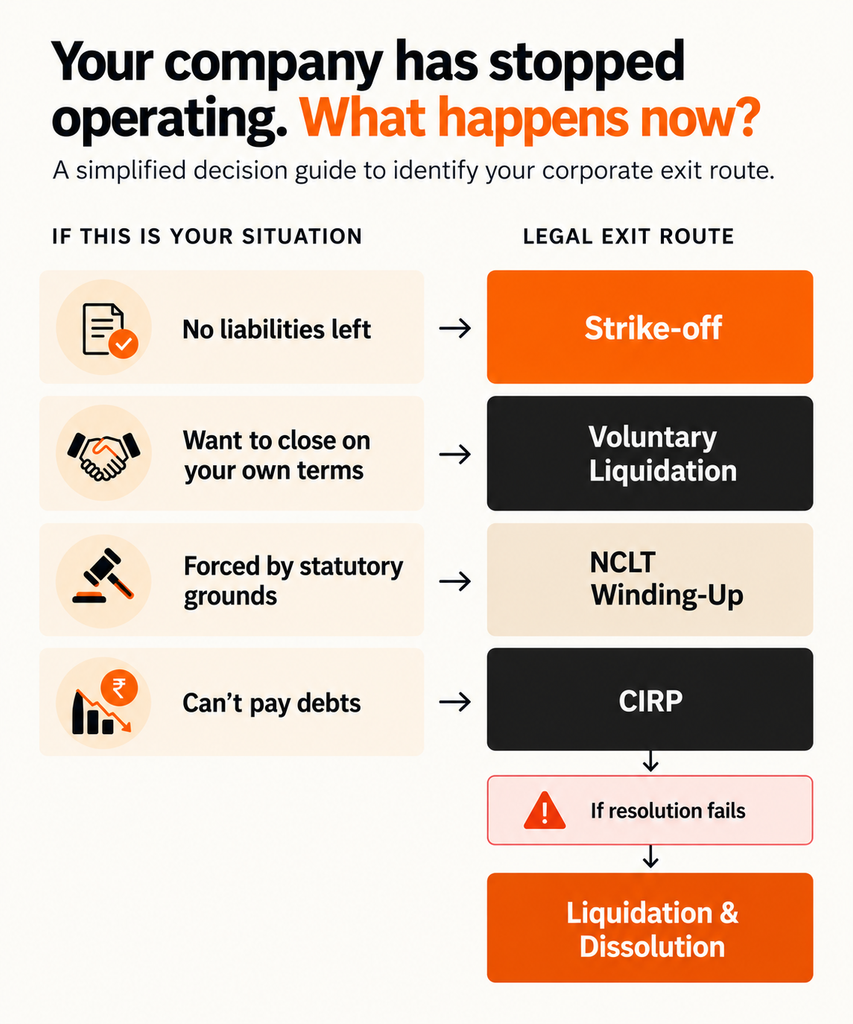
Image 1: Corporate Exit Routes: A Simplified Decision Guide
The real answer to the title question is here. A company doesn’t die when the app is gone, the office is empty or the founder quits tweeting. It expires when the legislation has taken one of these particular forks in the road and has formally ceased to be. Anything before it is just the story leading up to it.
References
- Insolvency and Bankruptcy Board of India, Order/Process: Dunzo Digital Private Ltd. (CIN U74900KA2014PTC075256),
https://ibbi.gov.in/claims/order-process/U74900KA2014PTC075256 (last visited Aug. 28, 2026).
↩︎ - Hike, backed by SoftBank Group, shut down and vanished from app stores on a Monday in January 2021, after founder Kavin Bharti Mittal announced the closure of Hike StickerChat on January 6. Tencent-Backed Hike, Once India’s Answer to WhatsApp, Has Given Up on Messaging, TechCrunch (Jan. 18, 2021), https://techcrunch.com/2021/01/18/tencent-backed-hike-once-indias-answer-to-whatsapp-has-given-up-on-messaging. ↩︎
- Companies Act, 2013, Sec. 248, No. 18, Acts of Parliament, 2013 (India), https://ca2013.com/248-power-of-registrar-to-remove-name-of-company-from-register-of-companies/. ↩︎
- Press Information Bureau, Ministry of Corporate Affairs, Centre for Processing Accelerated Corporate Exit (C-PACE) (2025),
https://www.pib.gov.in/PressReleasePage.aspx?PRID=2155051&lang=2®=48 (last visited Aug. 28, 2026). ↩︎ - Insolvency and Bankruptcy Code, 2016, Section 59, No. 31, Acts of Parliament, 2016 (India). https://ca2013.com/section-59-voluntary-liquidation-corporate-persons/. ↩︎
- Insolvency and Bankruptcy Board of India, NCLT Orders — Liquidation, https://ibbi.gov.in/en/orders/nclt?title=liquidation&page=3 (last visited Aug. 28, 2026) (recording voluntary liquidation dissolutions including S. Oliver Fashion India Pvt. Ltd., Ravi Cotton Factory Pvt. Ltd., and Whizdotai India Pvt. Ltd.). ↩︎
- Companies Act, 2013, Section 271, No. 18, Acts of Parliament, 2013 (India), https://ca2013.com/271-circumstances-in-which-company-may-be-wound-up-by-tribunal/. ↩︎
- Insolvency and Bankruptcy Board of India, Order/Process: BluSmart Mobility Tech Pvt. Ltd. (CIN U63030GJ2019PTC105970),
https://ibbi.gov.in/claims/order-process/U63030GJ2019PTC105970 (last visited Aug. 28, 2026).
↩︎ - NCLT’s Bengaluru bench directed the resolution professional of Think & Learn Pvt. Ltd. not to proceed with the Form G invitation for bids until August 31, following a challenge by the founders. Byju’s Insolvency: NCLT Halts Bid Process Amid Founder’s Challenge, Asianet Newsable (Jul. 24, 2026), https://newsable.asianetnews.com/business/byjus-insolvency-nclt-halts-bid-process-amid-founders-challenge-articleshow-72z1b1a. ↩︎
- Insolvency and Bankruptcy Code, 2016, Section 53, No. 31, Acts of Parliament, 2016 (India), https://ca2013.com/section-53-distribution-assets/. ↩︎
About the Author
Ms. Soumya Chaturvedi is a Learning Manager at Lawctopus Law School and an ex-Associate at IndusLaw, where she worked in the Capital Markets team. A 2021 graduate of NLU Odisha, she has previously interned with leading law firms including LKS, DSK Legal, and L&L Partners.